Financial Modeling, CMA Data & Detailed Project Reports (DPR) for Bank Finance
Risk Mitigation & Solvency
How Indian banks evaluate Credit Monitoring Arrangement (CMA) data, term loan project reports, and working capital limits. Structuring bankable financial models that withstand institutional credit risk scrutiny.
"“Bank credit managers do not fund optimistic promises; they fund verifiable operating histories, realistic CMA projections, and robust DSCR ratios.”"
Core Forms in Institutional CMA Data
- Form I - Existing & Proposed Limits: Summary of past sanctions, fund-based and non-fund-based (LC/BG) facilities requested.
- Form II - Operating Statement: 3-year past audited performance compared with 2-year projected revenue, gross margins, and EBIT.
- Form III - Balance Sheet Analysis: Current assets, tangible net worth, and long-term liabilities mapped against Reserve Bank of India lending covenants.
- Form IV - Comparative Financial Ratios: Current Ratio, Total Outside Liabilities to Adjusted Net Worth (TOL/ANW), and DSCR.
- Form V - Maximum Permissible Bank Finance (MPBF): Formal calculation under Tandon / Nayak Committee guidelines establishing legitimate working capital deficit.
Structuring Bankable Detailed Project Reports (DPR)
For term debt funding new manufacturing units, commercial assets, or plant expansions, a DPR must accompany the CMA data. A professional DPR details the Means of Finance, promoter equity contribution, sensitivity analysis against raw material cost volatility, and internal rate of return (IRR) validation.
📋 Professional Practice Advisory Note
Lav K Sharma & Co., Chartered Accountants delivers specialized Virtual CFO advisory, corporate debt structuring, statutory audit management, and direct tax compliance across India. For confidential consultation with our partners, connect directly with our office.
The 13-Week Rolling Cash Flow Forecast
Annual budgets are insufficient for managing working capital volatility. Well-run corporate finance desks rely on a rolling 13-week cash flow model updated every Monday morning:
- Weeks 1 to 4 (Deterministic): Known customer collection commitments, confirmed payroll obligations, statutory tax liabilities, and fixed vendor payouts.
- Weeks 5 to 8 (Operational): Anticipated project billing milestones, scheduled raw material purchases, and advance tax tranches.
- Weeks 9 to 13 (Strategic): Projected seasonal sales inflows and planned capex disbursements.
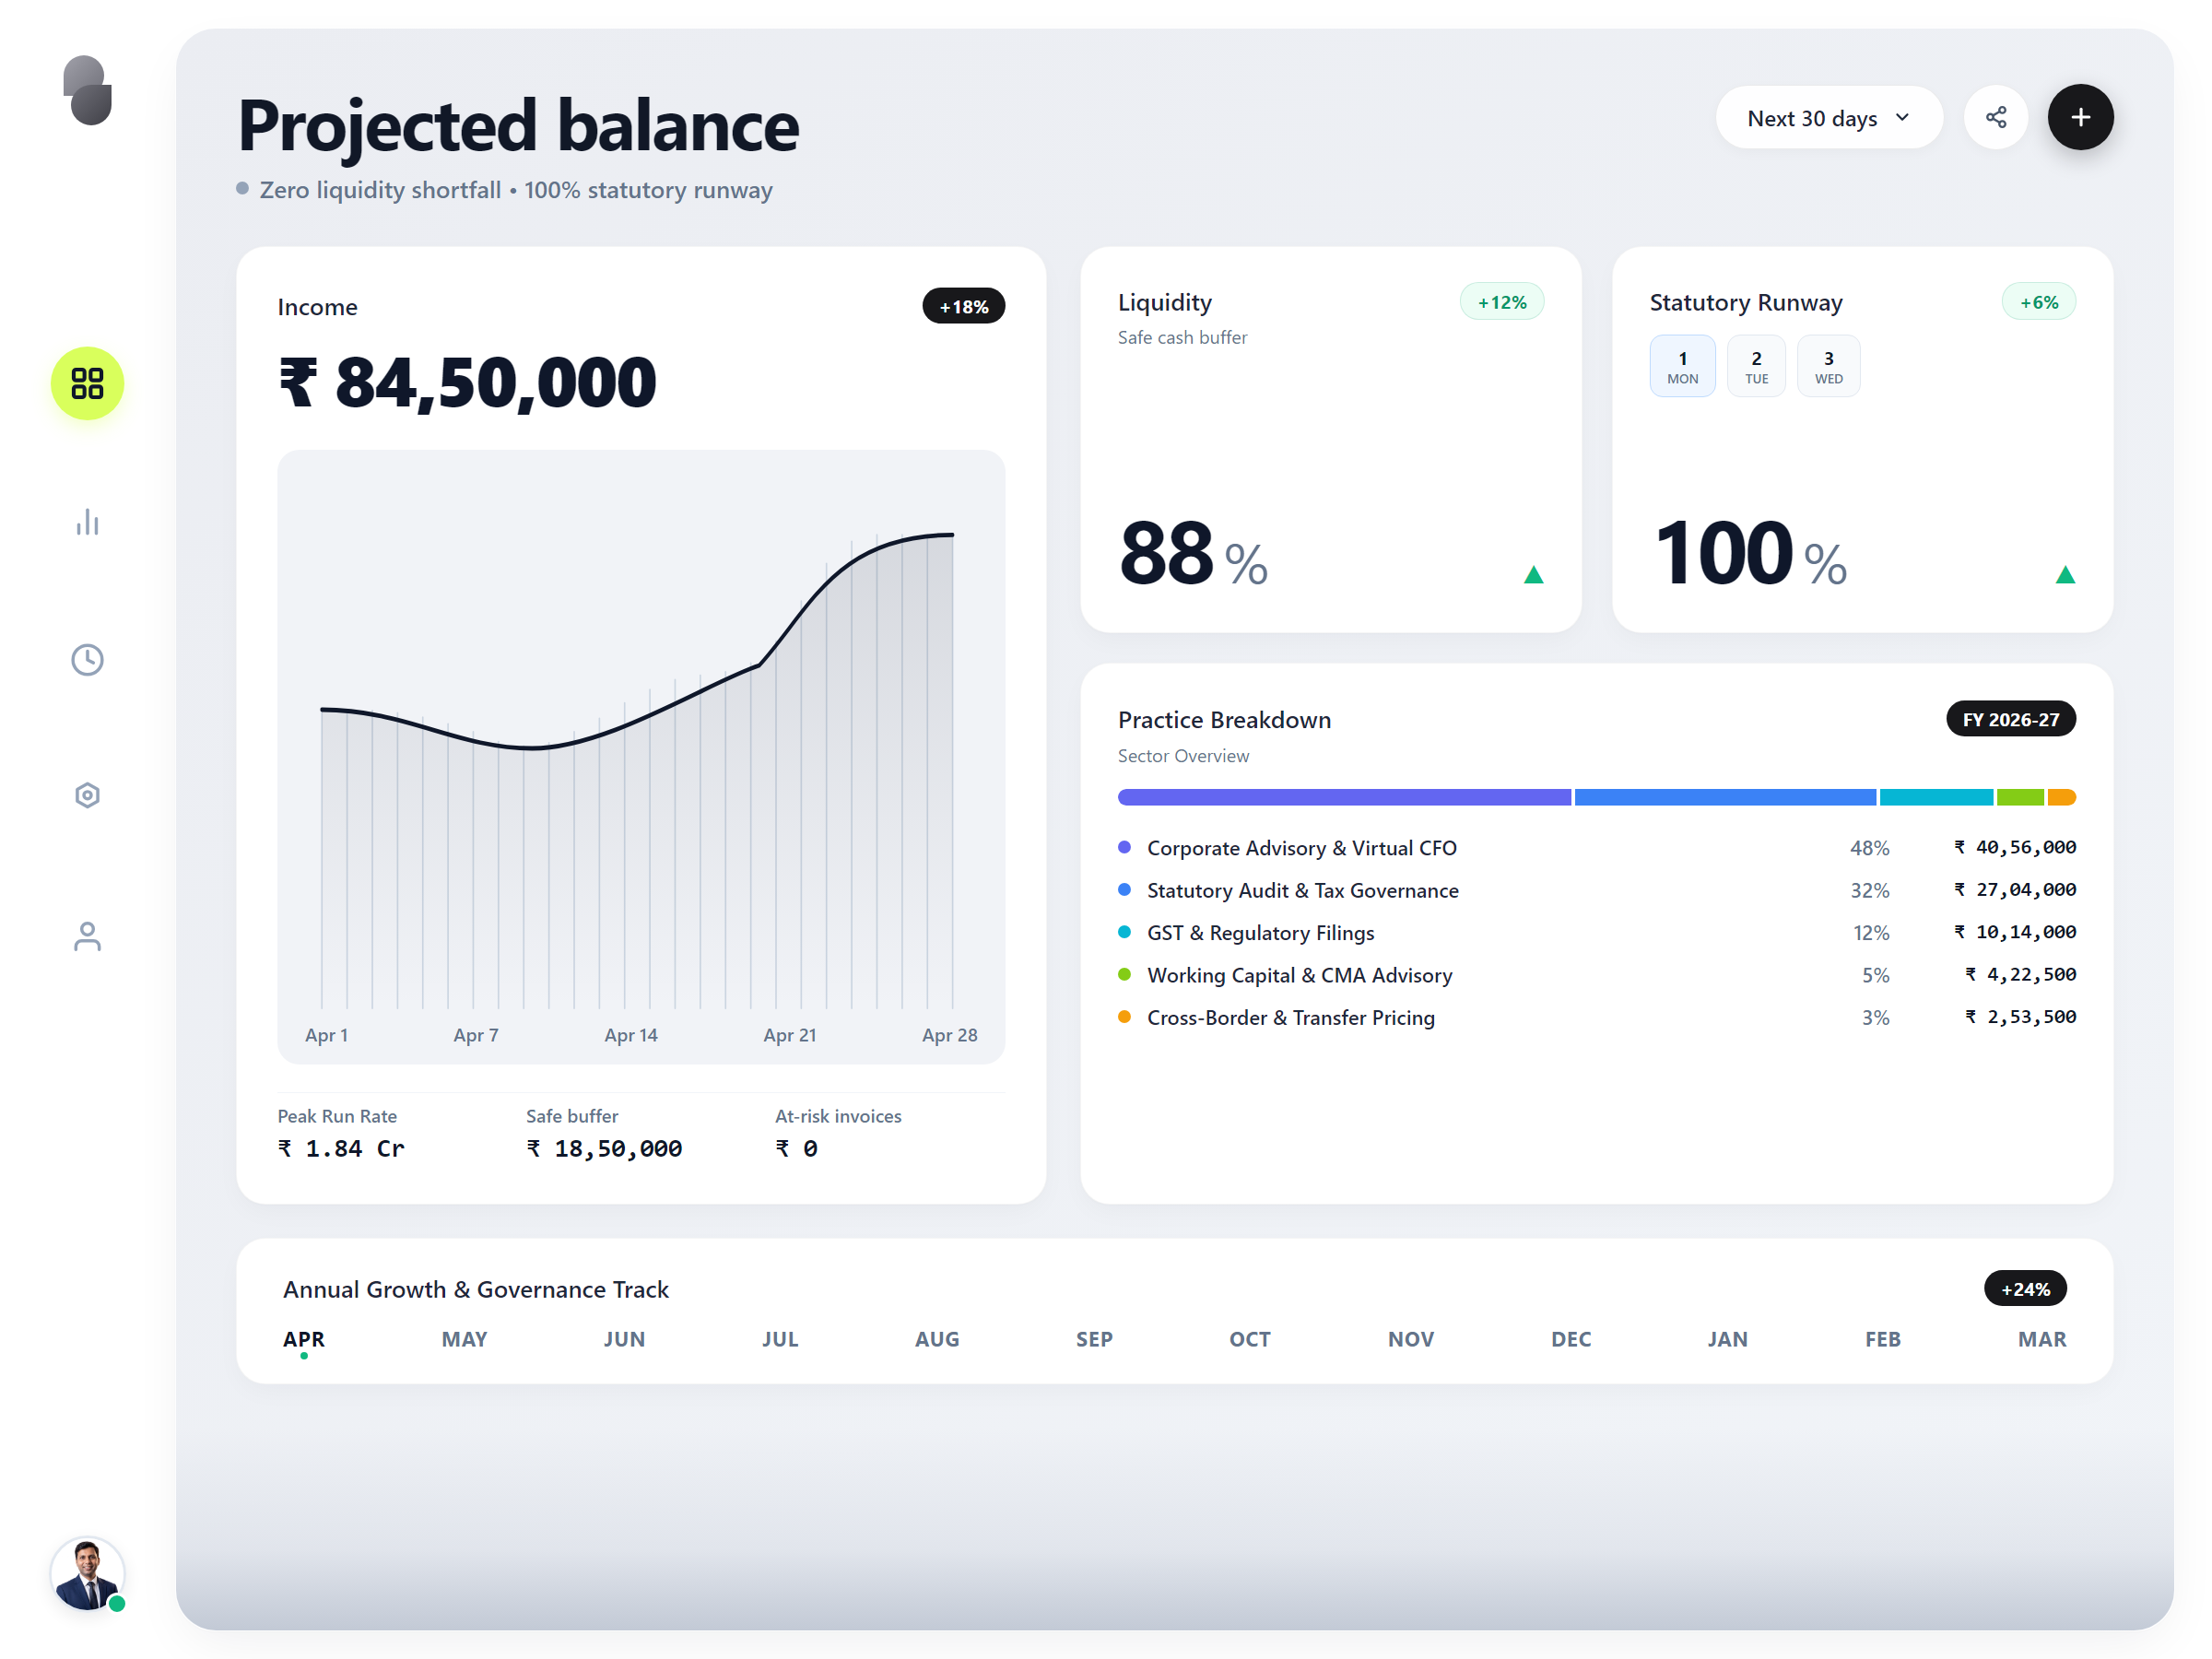
By rolling this 13-week projection forward each week, a liquidity shortfall is visible 8 to 10 weeks in advance—providing ample runway to adjust procurement, accelerate debtor recovery, or arrange promoter loans.
See also
Strategic Financial Leadership & Advisory
Lav K Sharma & Co. delivers Virtual CFO leadership, corporate tax planning, and statutory compliance discipline to growing enterprises across India.